
Will an annuity actually help me reach my retirement goals?
Honest answer: it depends on more than any illustration will show you. Your timeline, your tax picture, and the simple truth that life rarely unfolds as planned: goals evolve, needs change, surprises arrive. The right decision is one that still fits when they do. Our complimentary buyer's guide walks through the genuine strengths and the fine print, side by side, so you can make an informed decision.
Fixed indexed annuities are insurance contracts, not stock market investments. You do not directly participate in any index, and index-linked interest is limited by caps, participation rates, or spreads. Guarantees are backed by the claims-paying ability of the issuing insurer. Not FDIC insured.
The Annuity Buyer's Guide
Make an informed decision on all three types. Inside:
- MYGAs: when a guaranteed rate can beat a CD
- Variable annuities: the fee stack, in dollars
- FIAs: caps, participation rates & spreads, decoded
- Renewal-rate risk: the section to read twice
- Ten questions to ask before you buy
We’ll email you the guide, followed by a few short emails on choosing an annuity. Unsubscribe anytime. Add a phone number only if you would like a call. No obligation. See disclosures below.
What annuities do well, and what to know going in
MYGAs: a guaranteed rate
A multi-year guaranteed annuity pays a fixed rate for a term you choose, often higher than a bank CD of the same length. Interest grows tax-deferred until you withdraw it.
Fixed indexed annuities: growth with a floor
Interest is linked to a market index, up to a cap or participation rate. In a year the index falls, credited interest is 0%, so index losses do not reduce your contract value.
The trade-offs
Annuities work best for money you can set aside. Most have a surrender period of three to ten years, and caps and renewal rates can change. Knowing the terms up front is how you choose the right one.
Same market, three very different outcomes
A hypothetical contract with a 7% cap, annual point-to-point crediting. Illustrative only; caps vary by contract and can change at renewal.
Strong index year
The cap limits the credit. The 5-point difference is the cost of the floor.
Modest index year
Below the cap, the credit matches the index gain (excluding dividends).
Down index year
The floor holds at 0%. Note: rider fees, if elected, are still deducted.
Hypothetical example for education only; not a prediction or an offer of any product. Actual crediting depends on the specific contract's method, terms, and renewal rates.
One working session at our Alexandria office
Answer a few quick questions
A short fit check below, so we only book time that's worth yours.
Gather your documents
We'll send a one-page checklist: recent statements, existing annuity contracts or any annuity illustration you've been shown elsewhere, your Social Security estimate.
Meet in Alexandria
A working session, not a pitch. Plan for one to two hours, thorough rather than rushed. You leave knowing whether a fixed indexed annuity fits your plan, and second opinions on proposals you've received are welcome.
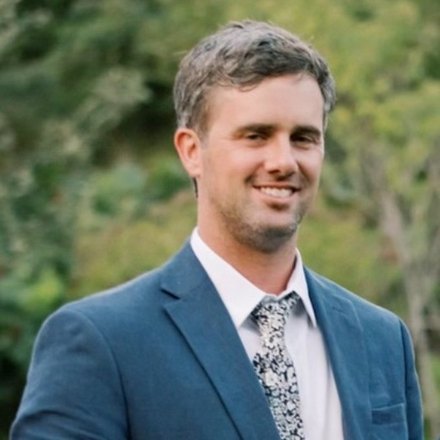
Brandon Lloyd, CFP®
Founding Partner & President, Mountain View Wealth Management
Brandon began his career in private equity in 2010 and went on to Wells Fargo Advisors before founding Mountain View Wealth Management. He is a CERTIFIED FINANCIAL PLANNER™ professional and holds a B.S. in Finance from James Madison University.
His approach to annuity questions is the same as the firm's approach to everything else: the recommendation comes after the full picture, which is why every working session starts with your statements on the table, not a product brochure.
See if a working session makes sense
Are you ready to strengthen your retirement portfolio?
A complimentary working session: your full picture, honestly assessed.
Which best describes your investable assets?
Savings, brokerage, and retirement accounts, excluding your home.
When are you looking to put money to work?
Do you currently have a financial plan?
A real one: income, taxes, investments, and estate working together.
How confident are you in that plan?
Gut answer is the honest one.
Have you been shown an annuity proposal or illustration elsewhere?
Either answer is fine. It just shapes the meeting.
You're a strong fit. Let's get it scheduled.
Choose a time below. Your confirmation email will include this checklist. Bringing it makes the meeting genuinely useful:
- Recent investment, retirement, and bank statements
- Any existing annuity or life insurance contracts
- Any annuity illustration or proposal you've been shown elsewhere
- Your latest Social Security benefit estimate
- Prior-year tax return (helps assess deferral value)
Working session · typically one to two hours · 6001 Tower Ct., Alexandria, VA 22304
Prefer to schedule by phone? (571) 368-6178
The guide is the right next step.
Based on your answers, we'd suggest starting with our buyer's guide rather than an office meeting. It will answer most first-stage questions. If your situation changes, we're here.
No pressure. The guide is yours either way.
Start with the buyer's guide on your own time. The ten questions at the back will serve you in any annuity conversation, with us or anyone else. If you change your mind, this page will be here.