
Mountain View Wealth ManagementAlexandria · Virginia
Financial Planning Guidance · (571) 368-6178
Whether it's a 401(k), 403(b), 457(b), TSP, or pension, leaving a job is one of the few moments you get to decide, on your own terms, what happens to your retirement savings. Leave it, move it, roll it to an IRA, or cash it out: each path has real trade-offs in taxes, costs, and flexibility. Our free guide lays them out in plain English, with the rules that protect your money and the mistakes that quietly cost people thousands.
Educational content only. Whether to leave assets in an employer plan, move them to a new plan, roll them to an IRA, or take a distribution depends on your circumstances, including fees, investment options, services, withdrawal rules, and creditor protection. Rolling over to an IRA may cost more than staying in your plan.
A free, plain-English guide. Inside:
Your guide opens right here. We may follow up with a few short emails on this topic, and you can unsubscribe anytime. No obligation, and no sales calls from a submission. See disclosures below.
Often allowed for balances over $7,000.
The plan has low-cost funds, or you left at 55+ and may need penalty-free access.
No new contributions, and old accounts are easy to lose track of.
If your new plan accepts roll-ins.
You want one account, strong federal protection, or a clean backdoor Roth.
You're limited to the new plan's fund menu and fees.
An account in your name that follows you.
You want broad choices, consolidation, and coordinated retirement planning.
Costs can be higher or lower; no loans; no Rule of 55.
A check to you, minus taxes.
There's a genuine emergency and no better source of cash.
Income tax, a 10% penalty under 59½, and decades of lost growth.
The four options are the same for nearly every workplace plan. A few rules are not, and some are easy to lose by moving money too quickly.
Public schools, hospitals, nonprofits.
Many older 403(b) accounts are annuity contracts with surrender charges. Ask for the schedule before you move it.
State and local government employees.
No 10% penalty on withdrawals after you leave, at any age. Roll it to an IRA and that advantage is gone.
Federal employees and the uniformed services.
Very low costs, penalty-free access at 50 for public safety employees, and Roth conversions inside the plan since 2026.
Lump sum or lifetime income.
The payout and survivor choices generally can't be undone, and married participants need a spouse's written consent for a lump sum.
And that's only the cost you can see. Left invested for 30 years at a hypothetical 6% return, that same $50,000 could have grown to about $287,000.
The guide covers the penalty exceptions, how to take only what you need, and what to do instead when cash is tight.
Hypothetical example: 22% federal bracket, Virginia's 5.75% top rate, and a 10% early withdrawal penalty. Actual taxes depend on your income. The 6% return is hypothetical, not a prediction or a guarantee.
Sent straight to your new account. Nothing withheld, no deadline, no tax.
20% is withheld, yet you have 60 days to deposit the full $100,000, covering the gap yourself, or the shortfall is taxed and may be penalized.
Our Social Security Claiming Guide and Retirement Readiness Checklist aren't available for download. We share them with people who are planning their retirement. Call (571) 368-6178 or request a review and mention them, and we'll send them your way.
A complimentary review: your plan, your options, compared side by side.
Choose a time below. Bringing these makes the meeting genuinely useful:
In person at 6001 Tower Ct., Alexandria, VA 22304, or by video
Prefer to schedule by phone? (571) 368-6178
Start with the free guide. It answers most first-stage questions, and the checklist at the back will serve you in any conversation. If your timing changes, we're here.
Read it on your own time. If you change your mind, this page will be here.
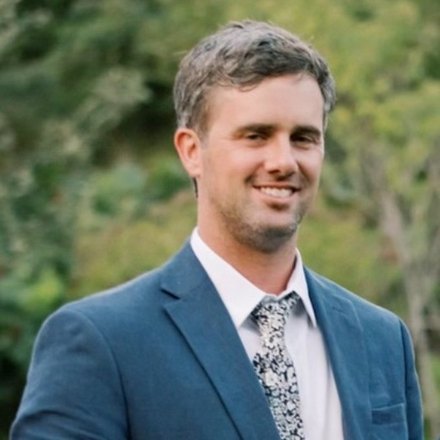
Founding Partner & President, Mountain View Wealth Management
Brandon began his career in private equity in 2010 and went on to Wells Fargo Advisors before founding Mountain View Wealth Management. He is a CERTIFIED FINANCIAL PLANNER™ professional and holds a B.S. in Finance from James Madison University.
In a complimentary retirement plan review, he'll compare your old plan, your new plan, and an IRA side by side, in writing. Sometimes the answer is to leave it right where it is, and he'll tell you when it is.